


Open an International Bank Account: Secure Your Finances Across Borders
An international bank account is a bank account opened in a foreign bank outside your country of permanent residence. It is a legal and practical tool for asset diversification, cross-border banking, multi-currency payments, and international business. To open an international bank account today, you do not need to be ultra-wealthy or relocate permanently abroad. For many clients, it is simply a smart step toward financial flexibility, capital protection, and better international banking access.
Excellent 4,6 out of 5

What Is an International Bank Account and How Does It Work?
An international bank account is a foreign bank account opened outside the client’s home country. It may be a personal account, a business account, a savings account, or a multi-currency account abroad, depending on the client’s goals.
This is not tax evasion. It is a lawful way to hold funds in another banking jurisdiction, diversify currencies, and access global payments infrastructure. The client remains responsible for tax reporting and disclosure obligations in their country of residence.
For many clients, the first step is simply understanding that a foreign bank account can be opened remotely and used for legitimate international banking, provided the compliance file is strong.
In practice, the account opening procedure usually looks like this:
 the client submits an application to open a bank account abroad
- the bank performs KYC, AML, and due diligence checks
- once approved, the client receives account details such as IBAN and SWIFT
- the account can be funded by wire transfer, internal transfer, or, in some cases, crypto-to-fiat conversion
- after activation, the account is ready for international payments, incoming transfers, and everyday banking use
Who Needs an International Bank Account?
This kind of account is useful for clients whose work, assets, or lifestyle already cross borders.
-
Expats & Non-Residents Useful for holding salary, savings, and reserves outside the country of residence and for managing an international bank account for non residents.
-
Digital Nomads & Frequent Travelers A practical tool for working in multiple currencies, reducing conversion losses, and managing life without depending on one domestic bank.
-
International Entrepreneurs & Business Owners Helps receive foreign payments, manage supplier transfers, and separate personal and business finances across jurisdictions.
-
HNWI & Investors Supports asset diversification, capital protection, and access to more flexible international banking services.
-
Crypto Investors Useful for clients who need crypto-friendly banking, crypto-to-fiat conversion, or a compliant route for funding from USDT or BTC.
-
Privacy-Conscious Individuals A non resident bank account or expat bank account can be attractive for those who value discretion, broader jurisdiction choice, and financial privacy within the law.
Key Benefits of Opening an International Bank Account
A client does not open a foreign account just for the paperwork. The value comes from flexibility, diversification, and the ability to operate internationally with fewer banking constraints.

Currency Diversification — Hold Assets in USD, EUR, GBP & More
An international bank account makes it possible to hold and manage several currencies, including USD, EUR, GBP, and sometimes CHF or others. This supports currency diversification and reduces reliance on one national currency.
Capital Protection & Asset Diversification
Holding all funds in one country creates legal, currency, and banking concentration risk. International banking helps spread that exposure across more than one jurisdiction.
Remote Account Opening — No Travel Required
Many partner institutions support digital onboarding, online KYC, certified document upload, and remote account activation. That means clients can often open a bank account abroad without a physical visit.
Privacy & Confidentiality — Discreet Banking Structures
Some jurisdictions offer stronger privacy, banking secrecy traditions, or more discreet account management than others. This does not eliminate CRS, FATCA, or tax reporting duties, but it can improve financial confidentiality and data protection.
Crypto-Friendly Funding — USDT, BTC, and Digital Assets
Some banks and EMIs support crypto-friendly banking, including documented funding linked to USDT, BTC, or crypto-to-fiat conversion. This is especially useful for clients who want regulated banking access for digital asset proceeds.
Global SWIFT Access & Multi-Currency Payments
A strong international bank account opening strategy gives access to SWIFT transfers, correspondent banking, international wire transfers, and broader payment flexibility across borders.
International Bank Account vs. Domestic Account — Key Differences
A domestic account and an international bank account do not replace each other. In a strong financial setup, they usually serve different purposes.
International Bank Account
- Better for asset diversification and international transfers
- Hold and manage foreign currencies
- Support for cross-border banking operations
Domestic Account
- Better for everyday local spending
- Convenient for bill payments within one country
- Best for local salary flows
Recommendation: A domestic account is usually best for everyday local operations. An international or foreign bank account is better for diversification, capital protection, global transfers, and work in multiple currencies. The strongest strategy is often to use both.
Talk to Us About Opening the Right International Bank Account
Choosing the right bank is not just about picking a country on a map. It is about matching your residency, banking goals, expected transaction volume, privacy needs, and compliance profile to the right institution. Uliana and our team help clients identify the most suitable route before they apply, which reduces the risk of rejection and saves time.
Contact an ExpertUliana Syva
Consultant for company registration, bank account opening, residency, and citizenship.
1000+
successful cases
13+
years of experience
International Bank Accounts by Jurisdiction
There is no single best country where international bank account solutions are accessible for everyone. The right jurisdiction depends on residency, nationality, budget, expected balance, preferred currencies, business model, and whether the client needs a personal or business structure.
Some clients prioritize Swiss-style prestige, others want easier remote onboarding in Georgia, the UAE, Hong Kong, Singapore, Panama, Vanuatu, or selected Caribbean jurisdictions. The right answer depends on fit, not fashion.
Traditional Offshore Banks
| JURISDICTION | ACCOUNT TYPE | VISIT | REG. TIME | CURRENCIES | CARDS | MIN. DEPOSIT | FEE | ACTION |
|---|
EMI Solutions
| JURISDICTION | ACCOUNT TYPE | REG. TIME | CARDS | FEE | ACTION |
|---|
How to Open an International Bank Account — Step-by-Step
For clients asking how to open an international bank account, the process is more straightforward than many expect. In many cases, it is also possible to understand how to open an international bank account online without leaving home.
Free Confidential Consultation
We review your residency, nationality, banking goals, source of funds, expected transfer volume, and preferred jurisdictions. This helps determine whether you need a personal account, business account, or multi-currency structure.
Bank & Jurisdiction Selection
We shortlist the most suitable banks or EMIs based on your profile, budget, minimum deposit, banking tools, and compliance requirements. This is where the difference between a good application and a weak one often begins.
KYC & Document Preparation
We help prepare the KYC package, including passport, proof of address, bank reference where required, source-of-funds explanation, and other certified documents. Strong preparation reduces delays and makes approval more likely.
Account Opening & Approval
The bank reviews the application, performs due diligence, and confirms the opening. Depending on the provider, this may take from a few business days to several weeks.
First Deposit & Account Activation
The client funds the account by SWIFT transfer, wire transfer, or, in some cases, crypto-linked funding. Once activated, the account is ready for internet banking access, incoming transfers, and everyday international use.
KYC & Required Documents for International Bank Account Opening
Every foreign bank account is opened through a compliance process. That is standard banking practice, not a special obstacle. The level of review depends on the bank, the jurisdiction, and the expected volume or balance.
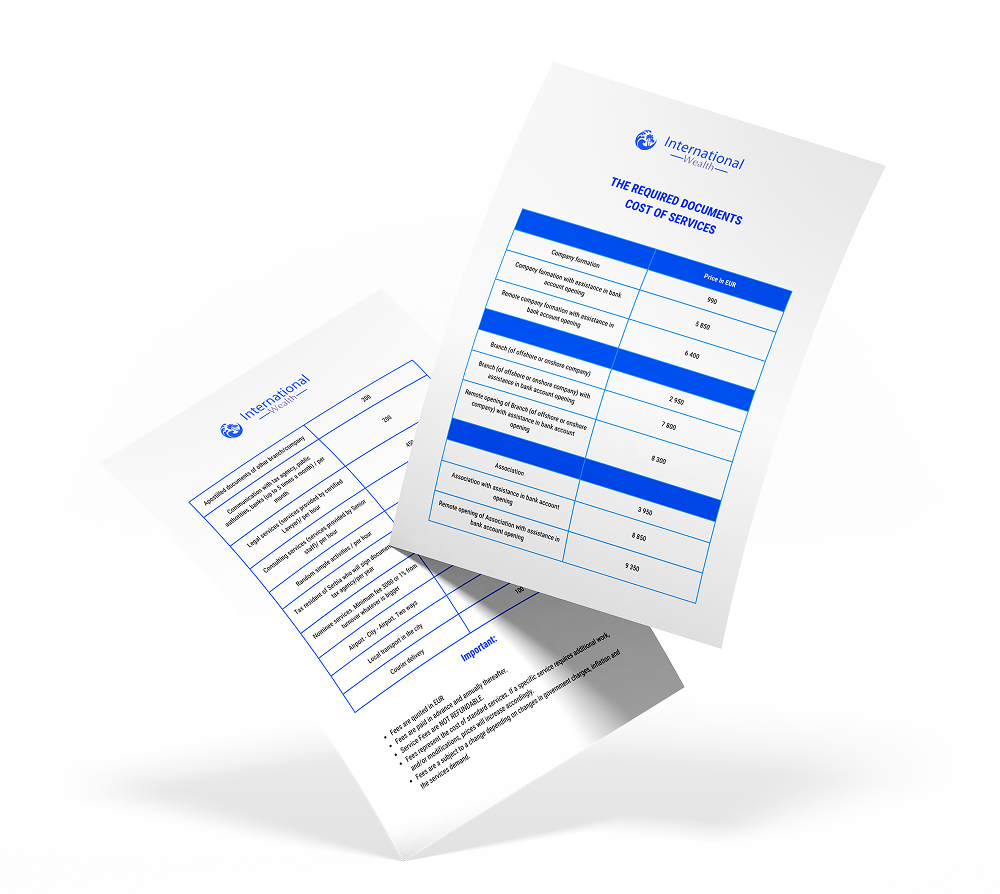
Typical documents include:
Certified or notarized copy of passport
Proof of residential address, such as a utility bill or bank statement
Source of funds declaration
Bank reference letter, where required
Proof of income or source of wealth in more complex cases
Additional due diligence forms if the bank requests them
Source of Funds vs. Source of Wealth
Source of Funds explains where the money being deposited comes from, such as salary, business income, sale of assets, or investment profits. Source of Wealth explains how the client built overall wealth over time. Some banks ask only for the source of funds. Others, especially for HNWI or larger deposits, may ask for both.
Our team supports the full compliance process, including KYC, AML, document review, and bank-facing preparation.
Why Choose Offshore Pro Group to Open Your International Bank Account?
Finding the best country with international bank account solutions is not about guessing. It is about knowing which banking jurisdiction is realistic for your case and which one is likely to waste your time.
Personalized Approach
We do not push generic solutions. We match each bank to the client’s residency, account purpose, transaction profile, and budget.
15+ Years of Experience
We have long experience in international banking, offshore bank account opening, and cross-border structuring for private and business clients.
Access to 50+ Banking Partners
We cooperate with licensed banks and payment institutions across 30+ jurisdictions, including providers that often do not accept direct cold applications.
Expert Compliance Support
Our team knows what banks want to see in KYC, AML, source-of-funds, and due diligence review. That lowers friction and helps reduce avoidable refusals.
Open Your International Bank Account Today
International bank account solutions today are not only legal, but often strategically necessary for clients who live, work, or invest across borders. A well-chosen account can support multi-currency banking, privacy, international transfers, crypto compatibility, and more resilient asset management. Contact us today for a free, confidential consultation. We will help you open a bank account in a foreign country and find options that fit your residency, goals, and budget.
Frequently Asked Questions
What is an international bank account and how is it different from a domestic account?
An international bank account is opened in a foreign bank outside your country of residence. It can support foreign currency holding, international payments, and cross-border banking. A domestic account is usually built for local everyday use.
Is it legal to open an international bank account?
Yes. It is a normal and legal financial practice for individuals and businesses. The client remains responsible for declaring foreign accounts and meeting tax reporting obligations in their home country.
Which countries offer the best international bank accounts?
There is no universal winner. Common options include Switzerland, Singapore, Hong Kong, the UAE, Georgia, Panama, selected Caribbean jurisdictions, and Vanuatu. The best country that offers international bank account solutions depends on your profile, not just the country’s brand.
How do I open an international bank account?
The process usually includes consultation, jurisdiction selection, KYC preparation, account approval, and first funding. The strongest results come when the bank is chosen based on the client’s real profile, not just on marketing promises.
How long does it take to open an international bank account?
Depending on the provider, the timeline may range from about three business days to four weeks. Simpler digital onboarding cases move faster, while more traditional banks may take longer.
What is the minimum deposit to open an international bank account?
It varies widely. Some providers have no minimum deposit, while others require several thousand dollars or more. The right option depends on the bank, jurisdiction, and type of account.
Can I open an international bank account online without visiting the bank?
In many cases, yes. Many providers support remote account opening, digital onboarding, online KYC, and video calls with compliance officers, especially for personal and lower-risk cases.
Can I fund an international bank account with cryptocurrency such as USDT or BTC?
Some banks and EMIs allow documented funding linked to crypto assets such as USDT or BTC. Usually, the bank will require blockchain history, exchange statements, or other proof showing a lawful source of funds.
Will my international bank account be reported under CRS or FATCA?
That depends on the jurisdiction, the account structure, and your tax residency. Some banks operate in non-CRS jurisdictions, but this does not remove your personal duty to report foreign accounts where required by law.
What currencies can I hold in an international bank account?
Many accounts support USD, EUR, GBP, and CHF. Some multi-currency structures support five, ten, or even more currencies, depending on the bank.