


Open an Offshore Merchant Account
An offshore merchant account helps companies accept online card payments, process international transactions, and build a more scalable payment setup for global growth. It is especially relevant for e-commerce, SaaS, digital services, and businesses that face restrictions, higher decline rates, or tighter local banking limits. We help clients select the right provider, prepare the compliance file, and launch a working payment solution with less friction and far fewer wrong turns.
Excellent 4,6 out of 5

Who Should Open an Offshore Merchant Account?
-
 E-commerce businesses selling internationally
-
SaaS and subscription businesses
-
High-risk business models
-
Service companies with international clients
-
Affiliate and lead generation businesses
-
Forex, gaming, crypto-adjacent, and restricted industries
-
Companies expanding beyond domestic acquiring limits
-
Businesses that need payment redundancy
What Is an Offshore Merchant Account?
An offshore merchant account is a payment acceptance solution that allows a business to process online card payments through a foreign acquiring structure rather than relying only on a domestic bank. It is not the same as a normal business bank account, and it is not the same as simply opening an offshore bank.
A merchant account is the part of the setup that receives card transactions from customers and routes them for authorization, capture, settlement, and risk review. In practice, the full structure usually includes three moving parts:
-
The acquiring bank
This is the financial institution that underwrites the merchant and settles approved transactions. In an offshore setup, the acquiring bank or acquiring partner is often located outside the merchant’s home country. -
The payment processor
The processor handles the transaction flow, communicates with card networks, and supports operational logic such as routing, recurring billing, and fraud controls. A strong processor is essential for stable offshore merchant processing. -
The payment gateway
The gateway connects your checkout page, shopping cart, or billing system to the payment processor. An offshore payment gateway allows online card acceptance and passes transaction data securely for approval.
Merchant Account vs Bank Account
An offshore merchant account should also be distinguished from an offshore bank account. An offshore bank account is used to hold funds, manage balances, send transfers, and support corporate banking. A merchant account is built specifically for card acceptance and payment processing. In other words, one stores money, the other helps you earn it.
For many clients, the right structure is not an either-or choice. It is a merchant solution plus a banking solution, working together. That is why a merchant account for offshore company structures often needs to be planned alongside settlement, reserves, compliance, and technical integration.
Get Personalized Guidance on Offshore Merchant Accounts
Choosing among offshore merchant account providers is not just about fees. It is about fit: your business model, chargeback profile, transaction geography, expected volume, website readiness, and compliance file all influence the outcome.
Contact an ExpertUliana Syva
Consultant for company registration, bank account opening, residency, and citizenship.
1000+
successful cases
13+
years of experience
Why Businesses Choose Offshore Payment Processing
Offshore payment processing gives international and higher-risk businesses more flexibility, broader provider access, and a more scalable way to accept payments across borders.

Better fit for high-risk or restricted industries
Some industries are treated cautiously by domestic banks even when they are fully legal. A specialized offshore high risk merchant account can provide access to acquiring partners that better understand subscription models, digital traffic, recurring payments, and chargeback-sensitive sectors.
Multi-currency settlement and global reach
Businesses selling across borders often need to accept payments in one currency and settle in another. Good offshore payment processing supports broader geography, more flexible settlement options, and more efficient international collections.
More flexibility in provider options
A local acquiring market may offer only a narrow set of providers. Offshore structures open access to more processors, more underwriting approaches, and more tailored routing logic for international business.
Business continuity and payment redundancy
If your company depends on one domestic provider, any policy shift, technical outage, or sudden compliance review can hit revenue immediately. Offshore redundancy reduces that dependency and strengthens resilience.
Better support for ecommerce and subscription models
An offshore merchant account for ecommerce can be a better match for cross-border stores, digital products, and subscription platforms that need recurring billing, tokenization, and broader card acceptance.
Higher acceptance potential for international cards
A well-structured setup can help reduce unnecessary declines when customers pay from different countries or card issuers. This is one reason businesses explore offshore credit card processing when domestic acquiring becomes too limiting.
How Offshore Merchant Processing Works
Understanding how offshore merchant processing works helps businesses see how payments move from customer checkout to authorization, settlement, and ongoing risk control.
Checkout to authorization flow
A customer enters card details at checkout. The gateway transmits the payment securely to the processor, which routes it to the acquiring bank and card network for authorization. If approved, the transaction is captured and queued for settlement.
Settlement flow and supported currencies
After approval, funds move through the settlement cycle and are paid out according to the provider’s terms. Depending on the setup, businesses may settle in USD, EUR, GBP, and other currencies. Reserve requirements and payout timing vary by provider.
Gateway integration and transaction routing
The gateway connects to your website, billing engine, or shopping cart. A strong offshore payment gateway can support flexible routing, recurring billing, fraud filters, and integration with common ecommerce systems.
Chargeback and risk monitoring basics
Chargebacks, fraud ratios, refund behavior, and transaction anomalies are monitored continuously. Good offshore merchant processing includes chargeback tools, risk alerts, and operational review to keep the account stable over time.
Compare Our Offshore Merchant Solutions
The right solution depends on your industry, traffic sources, expected monthly volume, chargeback ratio, company structure, and settlement preferences. Some businesses need a traditional acquiring relationship, while others benefit more from an EMI-linked or processor-led model.
| JURISDICTION | REG. TIME | CARDS | FEE | ACTION |
|---|
Strategic Considerations: Navigating Costs, Compliance, and Operational Stability
Understanding the Fee Structure: Why Quality Solutions Require Proper Investment
Reliable offshore acquiring is rarely the cheapest option, and that is normal. The provider is taking on higher underwriting risk, broader geography, and more complex monitoring obligations. Pricing usually includes MDR, transaction fees, setup fees, gateway fees, and sometimes monthly minimums.
Rolling reserve arrangements are also common. A reserve is not a punishment. It is a risk buffer that protects the acquiring side against future chargebacks, disputes, and delayed claims. For a business with healthy operations, this can actually support long-term account stability.
A professional provider should explain the fee grid from the start. No blurred math. No mystery charges appearing later like uninvited relatives at a wedding.
Safeguarding Your Business: Navigating AML, KYC, and Tax Compliance
KYC and AML checks are part of standard onboarding, especially for international and higher-risk models. These checks protect the payment ecosystem from sanctions exposure, fraud, and weak documentation. They also help serious businesses build stronger relationships with acquiring partners.
We assist with business descriptions, compliance questionnaires, ownership disclosures, and document preparation so the file is internally consistent. That matters because many applications are not rejected for being “bad businesses,” but for being badly explained.
We also pay attention to operational compliance standards such as PCI DSS, licensing status where relevant, and secure handling of client data. Strong compliance is not glamorous, but neither is watching revenue disappear because the onboarding package was messy.
Ensuring Longevity: How to Mitigate Banking Dependency and Operational Risks
A business should not depend on one processor, one bank, or one jurisdiction more than necessary. Payment redundancy helps protect continuity when a provider changes risk policy, experiences technical issues, or tightens underwriting unexpectedly.
Diversifying traffic and settlement routes across providers or jurisdictions can make the business more resilient. For growing merchants, this is often a strategic decision, not just a backup plan.
Chargeback monitoring is also essential. A stable account depends not only on approvals, but on how well the merchant controls disputes, fraud, refunds, and customer communication over time.
Finding the Perfect Fit: Assessing When an Offshore Solution Is Your Best Move
An offshore setup becomes especially relevant when domestic limits begin to block growth, when your industry is classified as high-risk, or when you need broader international reach than a local acquirer can comfortably support.
It is also a smart move for businesses that want settlement flexibility, global card acceptance, or a more scalable structure for cross-border sales. A strong merchant account offshore setup is not magic. It is simply a strategic tool for companies that operate beyond one local market.
Our 5-Step Process to Set Up Your International Merchant Account
Business and risk assessment
We review your website, business model, jurisdictions served, traffic sources, expected volume, average ticket size, refund profile, and compliance footprint.
Provider shortlist and pre-screening
We identify the most realistic providers for your business. This helps avoid mismatches and reduces the risk of failed applications.
KYC, underwriting, and document preparation
We help organize the ownership structure, business description, settlement preferences, compliance forms, and supporting evidence required for review.
Technical and contractual setup
Once approved, we coordinate the onboarding sequence, agreements, gateway logic, settlement terms, and reserve expectations.
Launch, monitoring, and optimization
After activation, we support the first stage of launch, monitor early performance issues, and help optimize the setup for international scaling.
Documents You Typically Need
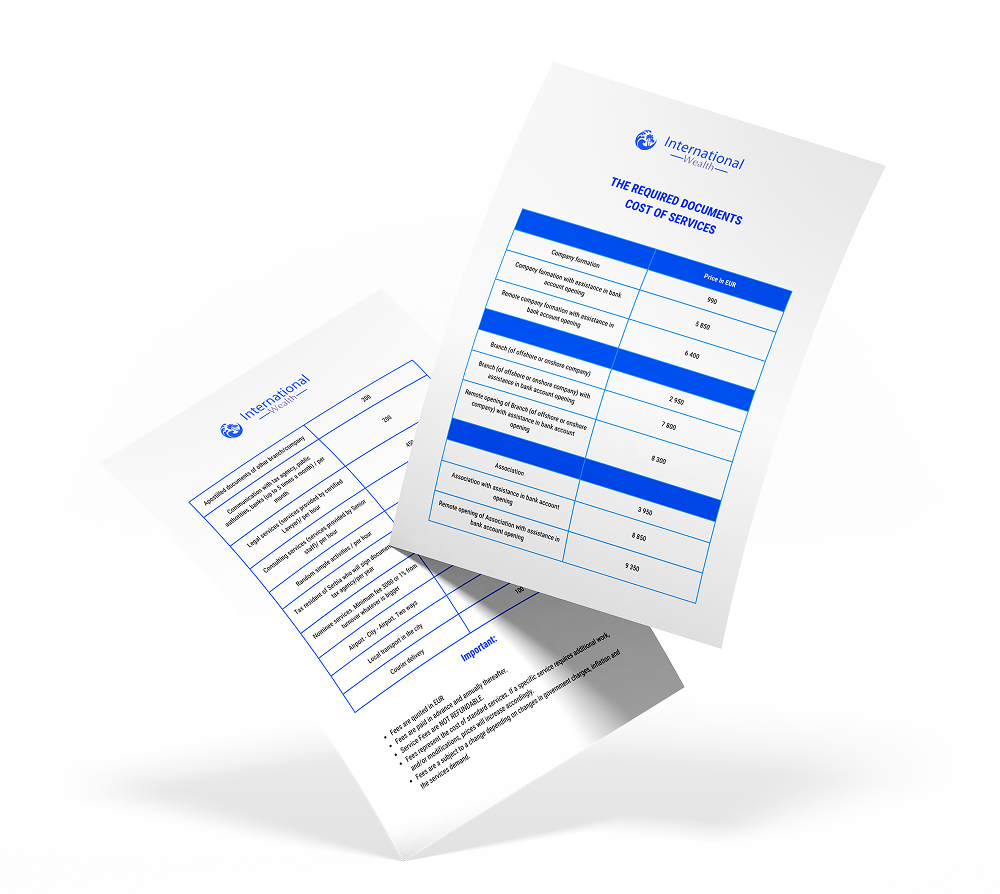
Banks, processors, and acquiring partners need a proper KYC file before approving an offshore merchant account. The exact checklist depends on the provider, but the following documents are commonly requested:
Certified copy of passport for the beneficial owner or directors
Proof of residential address
Source of funds and, where needed, source of wealth
Certificate of incorporation and company registration documents
Shareholder and director register
Website URL and business description
Refund policy, privacy policy, and terms of service
Recent bank statements
Processing history, if you already accept payments
Forecasted transaction volume and average ticket size
Explanation of target markets and customer geography
Contracts with suppliers or partners, if relevant
Tax identification details
Completed KYC, AML, and underwriting forms
For an offshore company with merchant account ambitions, the quality of the document pack is a major factor. Underwriting teams want to understand who owns the business, what it sells, how it gets paid, and how it manages risk.
Offshore vs. Domestic: Which Path Suits Your Business?
Choosing between offshore and domestic payment solutions depends on your risk profile, growth goals, target markets, and how much flexibility your business needs to scale safely.
The Offshore Advantage (Scaling & High-Risk)
Best for: International business, high-risk sectors, and companies that were rejected or constrained by local providers.
When to choose:
- Your business is categorized as high-risk
- You need to accept payments in many currencies
- Your local bank has strict volume limits
- You want broader international settlements and more flexible structure
Key benefit: Greater scalability and stronger resistance to single-provider disruption.
The Hybrid Strategy (Stability & Redundancy)
Best for: Larger e-commerce brands, expanding merchants, and businesses that already have local acquiring but need a second line.
When to choose:
- You already process locally and want backup capacity
- You want better acceptance for foreign clients
- You need risk diversification across jurisdictions
- You want to enter global markets without interrupting current sales
Key benefit: Better continuity, smarter routing, and more control over acquiring costs over time.
Why Partner with Us for Your Offshore Merchant Needs?
We help businesses avoid costly mismatches by selecting the right offshore merchant solution, preparing a stronger application, and supporting the setup from compliance to launch.
Exclusive provider shortlist based on your risk profile
We do not send the same list to everyone. Your shortlist is built around your industry, geography, volume, and underwriting reality.
Full application support: From documents to technical launch
We help from the first compliance draft to the operational go-live, including provider communication and onboarding structure.
Ongoing optimization for international scaling
A merchant setup is not “done forever” the day it is approved. We help businesses review reserves, declines, gateway logic, and expansion options as they grow.
Strategy built around your interests, not the provider’s
Our role is to protect the merchant’s position and recommend the structure that serves the business long-term, not the one that is easiest for a provider to sell.
Take Control of Your Financial Future Today
Build a payment setup that can actually support international growth. Whether you need a cleaner acquiring structure, better support for higher-risk activity, or a realistic path into cross-border card acceptance, we can help you evaluate the right solution. Contact us for a confidential consultation and a practical assessment of your chances before you apply.
Frequently Asked Questions
What is an offshore merchant account?
An offshore merchant account is a payment acceptance solution that allows a business to process online card payments through a foreign acquiring structure. It is designed for card acceptance and settlements, while a regular bank account is used primarily to hold and move funds.
Is offshore payment processing legal?
Yes, offshore payment processing is legal when the business activity is lawful and the company complies with KYC, AML, tax, and industry-specific rules. The key issue is not geography alone, but whether the structure is compliant and transparently documented.
How is an offshore merchant account different from an offshore bank account?
A merchant account handles card transactions, authorization, capture, risk review, and settlement. An offshore bank account stores funds and supports transfers. Many businesses need both. One collects revenue; the other manages it.
Do I need an offshore company first?
Not always, but in many cases yes. Some providers onboard only incorporated entities, while others can work with an existing international structure. If you want a merchant account offshore company setup, the company formation and payment structure should be planned together.
Can high-risk businesses get approved?
Yes, but approval depends on the business model, compliance file, website quality, chargeback profile, and jurisdictions served. A specialized offshore high risk merchant account or high risk offshore merchant account is often the right route for sectors that are rejected by ordinary providers.
What documents are needed to apply?
You usually need identity documents, proof of address, company formation papers, website details, ownership information, processing history if available, and compliance forms. Some providers will also request forecasts, policies, supplier information, or source-of-funds evidence.
How long does approval usually take?
It depends on the provider and the complexity of the case. Some lower-risk applications move quickly, while more complex or restricted industries take longer because underwriting and compliance checks are deeper. Sensible merchants plan for review, not miracles.
Is instant approval possible for offshore accounts?
In most serious cases, no true instant offshore merchant account approval should be expected. If someone promises offshore merchant account instant approval for a complex or high-risk business without real underwriting, that is usually a sign to slow down and look harder.
Do offshore merchant accounts cost more?
Often yes. Offshore solutions may include higher MDR, gateway fees, rolling reserve requirements, and more detailed monitoring. The higher price reflects underwriting risk, broader international exposure, and the operational support required for sustainable acquiring.
What currencies can I settle in?
That depends on the provider, but common settlement currencies include USD, EUR, GBP, and sometimes additional options depending on your structure and markets. Multi-currency settlement is one of the main reasons businesses explore offshore payment solutions.
Which countries are best for offshore merchant accounts?
There is no universal winner. The right jurisdiction depends on your business type, risk level, settlement needs, target markets, and compliance footprint. The best country is the one that matches your profile and has providers willing to underwrite it properly.
Can I connect a payment gateway to an offshore account?
Yes. In most cases, the merchant solution is built around a gateway integration, processor logic, and acquiring support. The exact setup depends on your platform, billing model, and provider requirements, but gateway connection is a standard part of launch.