An offshore bank account is an account opened by individuals or companies outside of their country of residence. Finding the right country for international banking isn’t as simple as it sounds. In reality, you need to find the right bank among all banks operating in a country that will accept you as a customer based on a variety of factors.
This guide to offshore banking presents ten of the world’s most popular locations to establish an offshore bank account. Locations have been selected based on practical criteria used to assess accessibility for non-residents, including online account opening and other factors such as entry requirements and associated costs. We have covered account currencies, payment systems, account anonymity, reporting requirements, and a host of other issues relevant to would-be account holders at offshore banks. Where possible, locations have been ranked by the range of account types they offer for legitimate purposes, including personal banking, business, investments, and private banking. Note, however, that not all banks in a given location will open an account for every applicant. Furthermore, having an account abroad does not automatically grant its holder tax exemption, anonymity, or asset protection.
Best Offshore Banking Countries: Quick Comparison
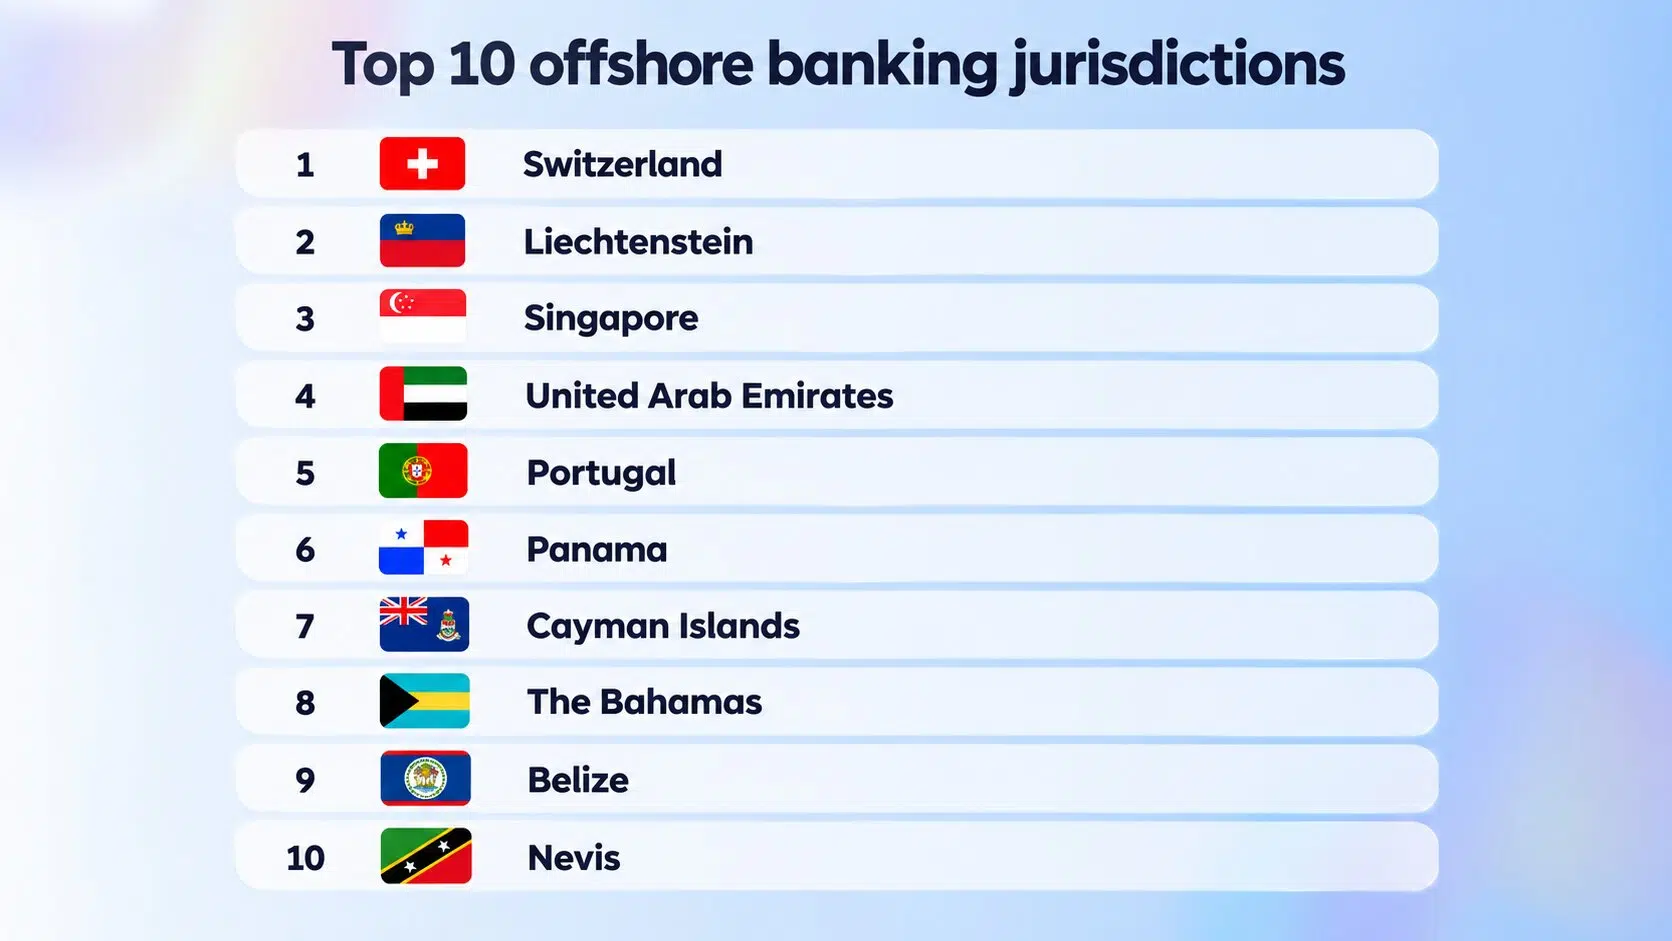
| Rank | Country | Best for | Typical entry level* | Remote opening | Non-resident access | Personal / corporate | Typical onboarding* | Main drawback |
|---|---|---|---|---|---|---|---|---|
| 1 |  Switzerland | HNW wealth management and investment custody | Often CHF 0 to over CHF 1,000,000+, depending on client profile | Sometimes; video or a meeting may be required | Selective | Both, with strong private banking | 4-12 weeks | High balances, fees and source-of-wealth scrutiny |
| 2 |  Liechtenstein | HNW families, foundations and succession structures | Commonly starting from CHF 100,000+; bank-specific | Sometimes through an intermediary or video KYC | Selective | Personal, corporate and structure-linked accounts | 4-12 weeks | Small bank pool and limited fit for daily transactional use |
| 3 |  Singapore | Asia-focused investors and established international businesses | S$350,000 for DBS Treasures; higher tiers from S$1.5 million and US$5 million | Limited for applicants without a Singapore nexus | Selective | Both | 3-12 weeks | Retail access normally requires a local pass or nexus |
| 4 |  UAE | Residents, UAE companies and internationally active entrepreneurs | Retail can start at low balances; non-resident/priority tiers may be much higher | Often digital for residents; non-residents are bank-specific | Moderate to selective | Both | 2-8+ weeks | Residence, local substance and business profile strongly affect approval |
| 5 |  Portugal | Non-residents needing a conventional EU/SEPA account | From EUR 250 at one major bank; terms vary | Available at some banks by video KYC | Moderate | Both | 1-6 weeks | Not a secrecy jurisdiction and usually not a multi-currency private-bank substitute |
| 6 |  Panama | Latin America-linked business, property and USD banking | Often bank-specific, can start from $3,000; relationship and local nexus matter more than a headline deposit | Usually physical or facilitated; digital routes often require local ID | Selective | Both | 4-12+ weeks | Documentation, local-nexus expectations and correspondent-bank friction |
| 7 |  Cayman Islands | Funds, captive insurance, investment structures and Cayman-connected clients | Bank-specific; private/institutional relationships may be substantial | Online channels exist, but some are limited to residents | Selective | Both, with strong institutional focus | 4-12+ weeks | Ordinary non-residents may need a Cayman nexus |
| 8 |  Bahamas | Private wealth, trusts and foreign-currency banking | Bank-specific; private banks may expect six- or seven-figure assets | Sometimes, subject to enhanced due diligence | Selective | Both | 4-12+ weeks | Smaller choice of suitable banks and exchange-control distinctions |
| 9 |  Belize | Smaller international deposits and straightforward foreign-currency accounts | Caye Bank currently publishes US$3,000 for selected accounts | Often remote, subject to certified KYC | Moderate | Both | 2-8 weeks | Smaller banking system and possible correspondent/payment friction |
| 10 |  Nevis | Nevis companies and clients with a genuine regional or structural link | Bank-specific; some international/private offers start much higher | Possible at selected banks, not guaranteed | Selective | Both | 3-10+ weeks | Very limited bank choice; a Nevis entity does not guarantee an account |
*The figures shown here are only for reference, and the published bank transfer charges can far exceed the amount actually transferred. Such charges are not always up to date and can vary greatly between institutions and even change from time to time. Therefore, please make sure you obtain a copy of the bank’s written terms and conditions before paying or transferring any money, for example, to form a company or open an account to carry out activities related to that account.
We shall examine your company formation application against current bank lending criteria for banks that offer the facility to issue certificates and transfer fees. In most instances it is necessary to approach 2 or 3 banks.
How We Ranked the Best Offshore Banking Countries
Primary evaluation criteria for offshore banking countries. Offshore banking accounts available within a country are the primary evaluation criteria. This extends to basic requirements for offshore banking, such as restrictions imposed by a country on residents and foreign funding restrictions, and all services that banks provide offshore, such as personal, business, investment, and private banking services.
We assessed the following factors:
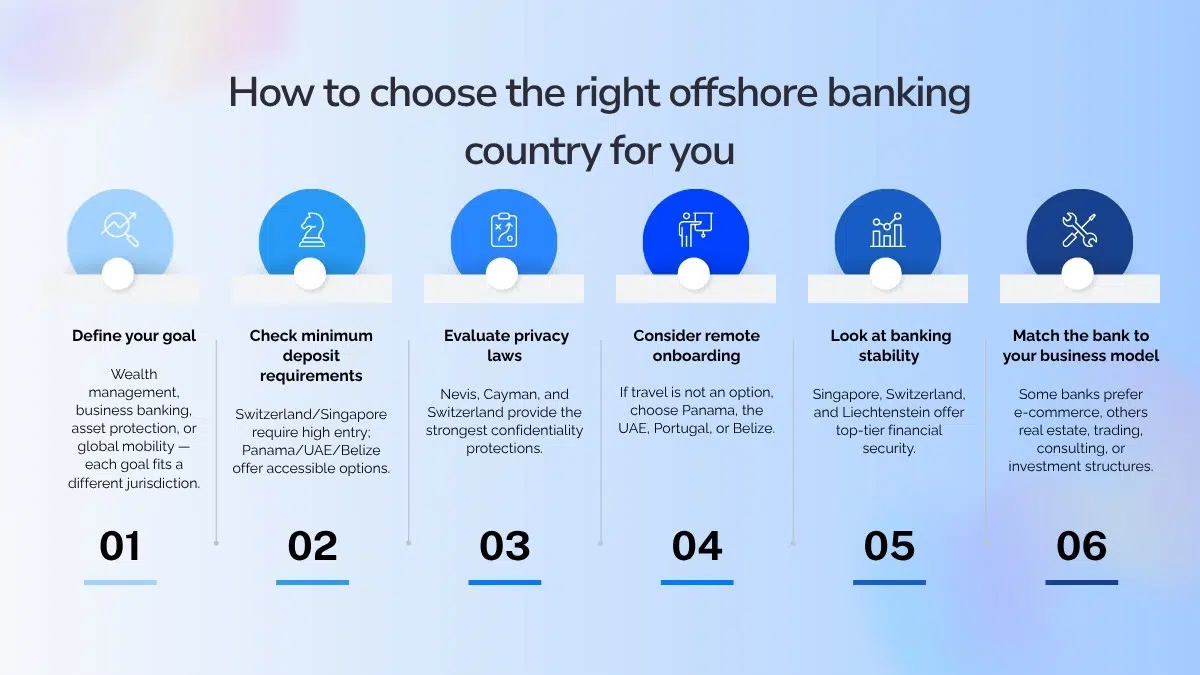
- Economic stability and resilience of the banking system;
- Regulatory reputation and standing with FATF;
- Accessibility of accounts for non-residents;
- Range of banking services offered (retail banking, business banking, investment, and private banking)
- Options for account opening: remote, intermediary-assisted, and in-person;
- Minimum deposit thresholds and balance requirements;
- Maintenance fees, transfer charges, and other associated costs;
- Time needed to open an account as well as verify capital/wealth of the account holder.
- Access to SWIFT, SEPA, and correspondent banking networks;
- Confidentiality measures alongside CRS/FATCA reporting obligations;
- Restrictions related to residency, nationality, sanctions, or industry.
Also with regard to service charges of offshore banking locations, there are big differences. Furthermore, the requirements for a remote account opening can vary considerably from one location to another. Thus, a thorough investigation is also required with regard to service charges and remote account opening.
Even within countries listed in high order, individual banks can differ significantly as to their conditions. Thus, while countries have been rated here on various bases, a higher-rated country does not automatically mean that it would be the best country for your needs, and possibly another country listed in lower order, like Belize, could be far more suitable because of lower minimum balance requirements to open or to maintain an account compared to, say, Switzerland.
What to Look for in an Offshore Banking Jurisdiction
Models within the banking sector are as diverse as savings products on offer and vary broadly between current accounts held by private individuals and high volume current accounts held by corporate entities. In many cases even well-established brands will charge differing amounts of fees on a like-for-like product between different geographic locations.
Offshore bank accounts for tax residents abroad can also be individually tailored with so-called premium services for international clients from all over the world. Corresponding bank packages are usually adjusted to the customer’s nationality, to his business abroad, as well as to potential other counterparties worldwide, including third-party account holders. As a rule, U.S. persons are also subject to the applicable requirements under FATCA when holding accounts abroad.
Here are four key elements that are frequently conflated:
- Confidentiality: While confidentiality of customers is generally respected by the Bank, no information will be divulged to third parties unless required by law or if the Bank is acting on your behalf in connection with a financial transaction, Banks dealing with anonymous tax residents must inform tax authorities and police worldwide of any suspected violation.
- In many tax havens, the taxation of assets in bank accounts held by residents and non-residents alike is a function of the account being held in that jurisdiction. The level and nature of such taxation can vary greatly from one account holder (tax resident) to another, based upon a number of different criteria, including their tax status, nationality, and the source of income from assets held in offshore bank accounts.
- Asset protection mostly will be put in place via structures of entities, trusts, and/or foundations and is covered by special legislation aiming to protect specific assets
- Some banks that allow online account openings still require additional documentation that is to be sent via post. In addition, a video conference with the bank representative may be required. Some banks also require the account to be opened via an introducer, and there are even accounts that require a personal meeting at one of the bank’s worldwide locations with the bank manager.
Top 10 Best Countries for Offshore Banking in 2026
The world’s most secure and reliable offshore locations have been reviewed and updated by our team. You can find more information on each location below. An offshore banking specialist is available to assist with opening bank accounts worldwide that suit your specific requirements.
1. Switzerland
Best for: High-net-worth individuals, families, and investment clients (e.g., family offices) who require a full range of wealth management services from their bank whilst conducting global currency trades through their account(s). All bank clients must have a meaningful banking relationship with the bank.
Why it made the list: While opening an offshore bank account in Switzerland is relatively easy, the big private banks are subject to numerous international banking regulations, which need to be observed. As a result, big private banks have established strict client acceptance criteria, which are partly counterintuitive to the purpose of opening an offshore bank account. For this reason, Swiss private banking has recently gone through significant changes. While it used to focus on secret bank accounts for anonymous asset protection, Switzerland’s private banking sector today delivers high-quality wealth management services to professional clients.
Who should avoid it: This banking environment would not be suitable for individuals holding small sums in their accounts. Furthermore, as outlined above, banks are looking for proof of the origin of monies being transferred into their accounts and satisfactory identification. Retail online banking services are typically designed for non-foreign resident clients holding accounts in CHF and residents and taxpayers in Switzerland. UBS, for example, now allows on-line account opening by its clients by means of an app. However, clients are required to reside in and also be taxed in Switzerland.
Non-resident account opening: Non-resident clients can also open non-resident accounts in Switzerland; in most cases certain countries are subject to restrictions imposed by individual banks. The minimum asset requirements for non-residents to open a banking relationship vary greatly between banks and even between different currencies. As an example, a bank may require CHF 50’000 for EUR-denominated accounts, while CHF 200’000 is required for USD-denominated accounts for non-resident clients.
Remote opening: For the majority of new clients the video ID certification process will be sufficient in order to complete the online account opening process. Acceptance of certified copies of identification will also be standard practice. A small number of our very wealthy clients may require a personal meeting with their private banker.
Typical minimum deposit: Typically clients have to deposit a minimum of CHF 0 to over CHF 1,000,000+, depending entirely on the type of bank and whether you are a resident or non-resident. Online investment platforms can have a lower minimum amount to open an account, but this would not grant a client a full private banking relationship.
Typical ongoing balance: The minimum balance required to avoid bank charges varies from bank to bank. In most cases, this amount is between CHF 20,000 and CHF 500,000 plus. Clients holding so-called “less accounts” typically hold smaller amounts of CHF. These accounts are offered at lower minimums but with less product choice than standard private banking accounts.
Typical onboarding time: Within 4-12 weeks. More complex constellations require more time.
Fees: Relationship fees, safekeeping fees, advisory and/or portfolio management charges, and individual transaction charges. We provide clients with an indication of the probable costs in advance based upon the client’s Assets Under Management (AUM) and transaction activity forecasted.
Personal accounts: Banks nowadays evaluate potential clients on the basis of market criteria when opening personal accounts. Clients need to show sufficient assets to be classified as a suitable client.
Corporate accounts: Swiss banks offer corporate current accounts for non-resident foreigners on a business basis. For this type of account, banks need the identification of beneficial owners of the company and some proof of the company’s cash flow to service the ongoing charges of regular transactions.
Private banking: Portfolio management of client assets either on an ongoing basis or via external specialized asset managers. Independent private bankers at UBS provide clients with objective financing recommendations for their existing investment portfolio and also for other financing alternatives.
Currencies and international transfers: Various currencies are available for current accounts and for money market accounts and related services. A broad range of different banking services can be made available for cross-border transactions.
Privacy and reporting: Banks distinguish clearly between clients’ confidentiality and clients’ tax secrecy. Within the scope of Swiss banking services, they are satisfied to report to the respective authorities in accordance with the automatically implemented information exchange under the CRS for so-called Phase 5 countries as well as for other countries outside of CRS. Additionally, the bank fulfills all FATCA reporting requirements for so-called US Persons as well as for other countries outside of CRS.
Main advantages:
- Extensive expertise in private banking and investment services.
- The profound experience in private banking is amplified by an ample offer of corresponding investments, extensive products, and optimal custody services.
- The extremely broad portfolio of currencies (over 30), including so-called exotic ones, for deposits, investments, assets, and their management.
Main drawbacks:
- Because of the high costs, these private banking services for new foreign customers are often unattractive.
- A number of restrictions may apply to foreign non-residents, depending on their country of origin.
- The transactional needs of the private banking client can become expensive over time.
Well-known banks & partners for foreigner non-residents: Online brokerage Swissquote has a long-established process in place for opening accounts for non-resident foreigners. Many of the large private banks, UBS, Julius Baer, Pictet, Lombard Odier, Vontobel, and Banque SYZ, for example, tend to concentrate on their core domestic client base and therefore attract fewer foreign non-resident clients.
Bottom line: Switzerland is one of the few locations worldwide where very comparable investments and long-term portfolio management for large sums of capital can be offered within competitive frameworks. For simpler transactional banking with minimal investable capital, however, Portugal, the UAE, or even Belize could be more appropriate.
2. Liechtenstein
Best for: High Net Worth Individuals — families, entrepreneurs, and beneficiaries of wealth utilizing foundations. Trusts and other transparent wealth planning structures as well as requiring investment management services.
Why it made the list: Liechtenstein’s financial system is uniquely positioned within the European Economic Area to offer banking services and first-class wealth management to its clients, using a wide array of holding structures, together with full-service family offices. Specialized expertise in all types and varieties of foundations and trusts is provided by the country’s banks. The offering contrasts significantly with that of its financial-center neighbor Switzerland in that it does not extend to a retail-banking product for the mass market and that it is offered to a select group of “high-end” clients either directly to them or via local intermediaries (lawyers, financial advisors).
Who should avoid it: Clients with low sums in current accounts, high volumes of trades on merchant accounts, people seeking a large variety of standard retail banking services, people seeking confidential treatment of their business affairs, or companies looking for Nominee Director/ Shareholder services (which are not offered).
Non-resident account opening: Yes, but selective and market-specific.
Remote opening: Online opening of non-resident accounts possible but subject to local market conditions and banks that allow it. It is then further processed by a local regulated professional (lawyer, etc.) in most cases. Video KYC is required for online acceptance. Online signing of digital documents required. Copies of identification are required for client acceptance. Occasional meetings with bank staff members at local banks are required in certain circumstances.
Typical minimum deposit: This varies from bank to bank but typically will be in the region of CHF/EUR 500,000 to 1 million and above.
Typical ongoing balance: The ongoing balance required to maintain a banking relationship is generally similar to the initial deposit amount for a relationship of this size.
Typical onboarding time: About 4-12 weeks. Here again, complexity and additional beneficial owners of accounts held in their names can increase the account opening process significantly.
Fees: Admin charges, safekeeping fees, individual service fees,, plus charges for payments, etc. Hence, for very small amounts it will not be worth our while to maintain a relationship with a client.
Personal accounts: The client will usually have a personal account within the wealth management relationship.
Corporate accounts: Banks in Liechtenstein have a wide range of different types of operating companies and holding companies available, as well as different types of foundations and trusts. Each type of structure must have a clearly defined purpose, and the beneficial owners must be clearly identifiable.
Private banking: Private banking services are offered by several financial institutions in Liechtenstein, including full-service banks such as LGT Bank and VP Bank. Private wealth management is offered by the wealth management divisions of these full-service banks for families and businesses worldwide. A range of products and services are offered by these banks in addition to portfolio management, including complex wealth management and succession planning.
Currencies and international transfers: All banks mentioned offer multi-currency accounts. Euro transfers within Europe are processed very fast and smoothly because of the EEA status of the country.
Privacy and reporting: The discretion of clients is respected and bank secrecy fully maintained. At the same time, however, banks are legally required to disclose information to governments and tax authorities worldwide and must also register foreign accounts of clients in their own database in line with CRS and FATCA regulations. In the Liechtenstein foreign account tax notification system, AN Sincura/Cod+Plus, all bank customers are required to disclose their foreign accounts to the government of Liechtenstein.
Main advantages:
- Strong alignment with foundation-, trust-, and family-wealth contexts;
- Stable European legal environment;
- Tailored private-banking model.
Main drawbacks:
- Limited choice between only a few banks with highly selective client acceptance policies
- Less suitable for daily trading company transactions;
- High compliance costs for complex structures.
Notable banks: LGT Bank, Liechtensteinische Landesbank, VP Bank, and SIGMA Bank.
Bottom line: For families with an already established wealth structure and succession plan, Liechtenstein might be an interesting option. However, for private individuals or even companies requiring private banking services, Switzerland’s offering in this area or even conventional banking services offered in countries such as Portugal with much lower minimum-balance requirements for current accounts might be more fitting.
3. Singapore
Best for: Singapore wealth market is suitable for investors who focus on Asia, high net worth individuals and established corporations with connections or operations in Asia, including management, counterparties, or ultimate beneficial owners.
Why it made the list: The country is one of the best to keep funds abroad for investors from Asia, for accredited/high-net-worth individuals, and for medium- to large-sized businesses with established operations and management in the region. This is due to the country’s well-established, sophisticated international wealth services platform that offers a variety of sophisticated financial services and products within a robust and very sophisticated regulatory environment that also allows for efficient multi-currency banking, among other things.
Who should avoid it: This would not be suitable for small non-resident clients with no local pass or business connections in Singapore and small investable capital. A fully remote general-purpose account for a foreign client from outside of Asia would not be suitable either, as there are practical challenges that need to be overcome to open an account.
Non-resident account opening: Restricted – Foreigner retail clients are opened on approval of a foreigner’s application for a Singapore pass (or equivalent). There are also distinct eligibility criteria for opening accounts as cross-border wealth clients.
Remote opening: Often digital for eligible local residents and pass holders; limited and bank-specific for pure non-residents.
Typical minimum deposit: DBS’s minimum fund sizes are S$350,000 for DBS Treasures, S$1.5m for DBS Treasures Private Client, and US$5m for DBS Private Bank. Other banks will have their own minimums.
Typical ongoing balance: Same as the minimum Assets Under Management (AUM) for the relevant wealth-tier offering.
Typical onboarding time: 3-12 weeks depending on a customer’s local connections, the complexity of their wealth structures, and the corporate due diligence required on their behalf.
Fees: The fees for retail products are reasonable, while those for private banking include fees for custody, advisory, management, and specific investment products. For wealth clients with accounts below DBS’s revised minimum AUM for certain relationships, the annual fees are specified in a fee schedule published by the bank.
Personal accounts: Personal banking products are offered to Singapore residents and foreign individuals who hold valid passes in Singapore and who have a minimum sum to place in the account. Wealth clients are served by selected wealth managers.
Private banking: For corporate accounts, we have strong connections with companies that have credible Asia-based operations with local management and a a client base. We are skeptical of “shell companies” opened with no legitimate basis for conducting business.
Privacy and reporting: While Singapore’s financial information is guarded and maintained confidentially, it is nevertheless in compliance with CRS (Common Reporting Standard) as well as FATCA (Foreign Account Tax Compliance Act) regulations. As such, confidentiality of customers does not translate to anonymity.
Main advantages:
- Strong connectivity to Asian investments and business opportunities;
- Sophisticated digital infrastructure paired with multi-currency services;
- Singapore’s well-established banking system for wealthy individuals and strong private banking services provided.
Main drawbacks:
- Generally foreigners who have no link whatsoever to Singapore will face strict selection criteria by Singaporean banks.
- High minimum deposits required for fully serviced private banking solutions offshore.
- Industry-specific and country-risk controls can be stringent.
Notable banks: DBS, OCBC, UOB, Bank of Singapore, and selected international private banks.
Bottom line: In summary, if you have Asia-linked wealth or business interests, Singapore would be the better location for managing your wealth. Alternative locations to consider for private wealth management are the UAE for Middle East/Africa-connected clients and Switzerland for European wealth management opportunities.
4. United Arab Emirates
Best for: UAE residents, free-zone or mainland companies with real local operations, international entrepreneurs, and high net worth individuals in Dubai or Abu Dhabi (or other parts of the MENA region) who also utilize those locations as a business hub.
Why it made the list: The country offers multi-currency banking, an enormous expat population, and great connectivity to the rest of the Middle East, Asia & Africa. The benefits are extreme for those that have residency, physical premises, managers on the ground, or even sensible business activities in the country.
Who should avoid it: This option is not suited for non-residents of the UAE who require an unrestricted current account without any connection to the country and newly formed companies that do not have contracts, office space, employees, or any other genuine business activity within the UAE.
Non-resident account opening: Non-residents can open a savings account or even benefit from a priority banking product. Current accounts, on the other hand, are reserved for residents that hold physical premises; banks can issue checks to residents who hold current accounts at the bank where they have a business.
Remote opening: it’s common for residents to open accounts remotely. Non-residents are subject to the bank’s policies on non-resident account opening. They may be required for a personal visit, to provide an introducer, etc., as well as additional verification checks.
Typical minimum deposit: Typically the basic account held by residents will require salary payment into account or a minimum average balance of approx. AED 3,000. The priority/savings type account held by non-residents will typically require a minimum deposit of between AED 100,000 and AED 500,000 or more for accounts within private banking.
Typical ongoing balance: This will vary depending on account type but often there is a minimum average balance required or even a monthly fall-below fee in the account holder’s currency.
Fees: A variety of fees are typically charged, including the monthly fall-below charges, overseas transfer charges, and business package fees. For more information, see Emirates NBD’s key-facts statement, which notes that the bank’s eligibility criteria and minimum balance required for products offered to residents differ from those offered to non-residents.
Personal accounts: Wide coverage for residents. Few options available to non-residents.
Corporate accounts: Corporate current accounts are available for companies but are subject to evaluation of economic substance, such as the presence of trade licenses, physical offices, contacts with counterparts, expected turnover, and owners’ experience.
Private banking: Private banking services provided by prominent local and international banks to high-net-worth individuals.
Currencies and international transfers: UAE Dirhams (AED), US Dollars (USD), Euro (EUR), and Great British Pounds (GBP). Swift services, wire transfer, and trade finance (L/C’s, DD’s, etc.) are also available for all types of businesses.
Privacy and reporting: The UAE bank accounts are subject to the UAE’s Anti-Money Laundering (AML) Laws & fulfill all CRS & FATCA requirements. Therefore, it is NOT a no-reporting jurisdiction for non-resident account holders worldwide.
Main advantages:
- Location in the prime business area of the MENA region.
- The large range of banks in the UAE and good online offerings;
- A synergistic personal-and-corporate ecosystem for genuine residents and businesses to prosper.
Main drawbacks:
- Non-resident products tend to be more limited;
- Newly established companies with little economic substance may encounter problems and even delays or even rejections from banks.
- Minimum-balance penalties alongside compliance requests can be considerable.
Notable banks: Emirates NBD, First Abu Dhabi Bank, Mashreq, ADCB, and RAKBANK. Capital Union Bank should not be listed as a UAE bank; it is licensed in the Bahamas.
Bottom line: We recommend opening an account in the UAE if you are a resident or have meaningful business activities there. Consider Singapore for investing in Asia or Portugal for easier account openings in the EU.
5. Portugal
Best for: This country is best for non-residents, expats, and other people with international connections who open a regular euro currency account held in a mainstream bank in an EU country and conduct SEPA payments from there.
Why it made the list: Portugal’s appeal to non-residents has helped make the country one of the strongest locations for international banking services to be opened by non-residents, particularly those who have relocated and require banking services in a Euro currency accounting structure within an EU country but are also considering property investment in their home country of Portugal.
Who should avoid it: This will not be the best option for individuals seeking anonymous offshore banking, general offshore banking, tax haven countries, or premier multi-currency accounts that provide access to high-end private banking services.
Non-resident account opening: As a non-resident, you will need to provide a tax number, address, occupation, and proof of source of funds for your account opening.
Remote opening: The ability to open up a non-resident account remotely online via identification tools or even video call with a bank representative can also be a possibility. Again, ID documentation required will be country-specific and even bank product-specific.
Typical minimum deposit: Major international banks are willing to open Adult ‘Resident’ / ‘Non-Resident’ accounts for a minimum deposit of approximately €250. Such accounts at smaller regional banks might require minimums of different account types and even vary amongst individual banks.
Typical ongoing balance: Retail banking offers are characterized by low minimum ongoing balance requirements. However, certain packages might require higher amounts, which are charged by the bank by means of certain fees or by other conditions and terms.
Typical onboarding time: Account opening for a normal current account takes 1-6 weeks (in rare cases even longer).
Fees: Bank charges for active accounts held in “Resident”/”Non-Resident” status normally amount to around €5-10 per month. Some accounts and packages, however, carry an annual charge (e.g., for the Millennium BCP “Star Account / Simple & Solid Star Accounts” current accounts—published, pre-applying any applicable discounts — is €99.84 per annum).
Personal accounts: These are of particular interest given that Portugal is considered to be one of the world’s best countries for people to relocate to in order to continue to run a business or investment from overseas and continue to receive income from within SEPA countries and hold income in a euro bank account.
Corporate accounts: Corporate accounts can be opened, but account opening for a corporate entity cannot be completed remotely. Detailed information will be required regarding the purpose for which the company is conducted, the full ownership structure, and the managing directors (including IDs) of the company.
Private banking: Private banking services are available in Portugal. However, when compared to other countries in the market such as Switzerland or Liechtenstein, these services are not as comprehensive for cross-border corporate clients.
Currencies and international transfers: Clients can open a fully planned euro bank account to take advantage of full SEPA services; foreign currencies are available on a bank-by-bank basis.
Privacy and reporting: The country adheres to the same reporting standards applicable throughout the EU under the Common Reporting Standard (CRS) in addition to the requirements stipulated by FATCA. The previous regime of the Non-Habitual Resident (NHR) has in the meantime been abolished and has been replaced by a new system of Scientific Research and Innovation in Financial Institutions (IFIICI), which even for bank accounts is strictly separated from the tax resident status.
Main advantages:
- Accessible EU/SEPA banking options tailored for select non-residents;
- Low entry point compared to traditional private-banking hubs;
- It’s a great location for people relocating to be able to continue to do all their Euro transactions and property investments.
Main drawbacks:
- It’s not considered an offshore location with special privacy/privacy TAX/‘none of the above’ characteristics.
- Particular attention needs to be drawn to the eligibility criteria for remote opening of accounts and the required documentation for the relevant products.
- Opening a non-Euro country account in a non-EU area country such as Switzerland or Liechtenstein is not very strategically successful in terms of global wealth management.
Notable banks: Millennium BCP, Santander Totta, Novo Banco, Banco BPI, and Caixa Geral de Depositos.
Bottom line: Portugal remains one of the few solid locations within the EU/SEPA region where non-resident individuals can open and operate euro transaction accounts. For a more comprehensive range of private wealth management services in the region, consider Switzerland and/or Liechtenstein, while outside the EU, consider the UAE to establish a business.
Open an Offshore Bank Account
Access secure international banking, multi-currency accounts, and flexible solutions for personal or business needs.
6. Panama
Best for: Panama is extremely advantageous for a variety of entrepreneurs, property owners, and companies from all over the globe conducting legitimate business within Panama (Latin America) or even trading in USD and doing business in the Latin American region.
Why it made the list: Panama is featured in this list for several good reasons. The country has a USD-based economy and an extensive Latin American banking network,, which serves green card holders, Latin America-based businesses, and property owners who do business in this area. The banking system in Panama provides significant value to those who engage in trade and conduct business in USD throughout Latin America, and in addition to that, it also supports global commerce. Although Panama was removed from FATF’s increased monitoring in October 2023, it is still under heightened scrutiny, and as a result, all the banks here enforce enhanced due diligence on new as well as existing customers.
Who should avoid it: Those without connections to Latin America, those who do not speak Spanish and would like everything to be explained in detail for opening an offshore structure remotely online and opening offshore bank accounts.
Non-resident account opening: Accounts for non-residents in Panama can be opened using proof of status, as well as property ownership, trade activities, professional activities, or business.
Remote opening: Yes, but as noted above, only via specific online channels for non-resident foreign nationals (i.e., green card holders and others abroad from outside Panama) holding an existing relationship with banks here or with a local ID number. A local contact would also likely be required to physically open up an account at a bank here in Panama.
Typical minimum deposit: Banks set and amend minimum deposit requirements from time to time. The minimum deposit for new customers opening low-deposit accounts can vary considerably between banks and accounts and will often be higher than the printed minimum account opening amount where recent activity or an existing relationship with the bank helps to open the account sooner. Always check current minimum deposit amounts with individual banks rather than relying on old information.
Typical ongoing balance: Ongoing account balance requirements vary for different types of accounts offered by banks, even for current accounts, and need to be specifically verified with the respective banking institution.
Typical onboarding time: This can take anywhere from 4 to 12 weeks, depending on whether any documentation requires certification via an apostille and then translation into Spanish as well as any additional items considered required by the bank.
Fees: Although the charges for maintaining an account and for wire transfer (as an outgoing transaction) are competitive, there are additional charges for items such as certification, obtaining an apostille or translation, and also for an introduction by the bank.
Personal accounts: Personal accounts can be established for non-residents that have sufficient ties to Latin America and can have a banking hub in the region.
Corporate accounts: Corporate bank accounts in Panama will be approved to open a business account by the bank’s brokerage or correspondent office when provided with appropriate contracts, invoices, corporate shareholder agreements, and certificates of incorporation, as well as other logical documentation. Such bank accounts in Panama are typically opened by corporations to conduct regional trading and to own assets in Panama.
Private banking: Local banks and international institutions operating in Panama offer a complete variety of financial services to individual clients of superior caliber and financial means.
Currencies and international transfers: Although several currencies are accepted by the bank (among them USD), the operations are managed from the bank’s USD regional hub. Wire transfers are made through the bank’s correspondent network.
Privacy and reporting: Cross-border transactions are subject to the same reporting requirements as transactions carried out entirely within Panama by its banks under the Common Reporting Standard (CRS) agreed upon by more than 100 countries as well as the reporting requirements under agreements signed by the Republic of Panama with regard to FATCA (Foreign Account Tax Compliance Act) requirements to report income worldwide by all taxpayers within Panama, including foreign owners of assets located in Panama and residents abroad in other countries, and to meet all tax and other reporting requirements as a taxpayer both within and outside of Panama.
Main advantages:
- USD-based regional hub;
- A substantial banking market relative to other offshore jurisdictions;
- Significant advantages compared to alternative offshore locations;
Main drawbacks:
- Although it seems very convenient for some customers, it’s not always accessible for them.
- By opening accounts, foreign counterparts will have to meet with special conditions when transacting with foreign payment account holders based in Panama;
- Even very connected foreign counterparties have to meet with special conditions to conduct transactions with the foreign payment account holder based in Panama.
Notable banks: Some of the notable banks for foreign customers are Banco General, Banistmo, BAC International Bank, Multibank, and Citibank (although it is worth noting that it is a retail bank and that you would need to assess the client base).
Bottom line: Accounts in Panama are mostly for USD-denominated transactions within Latin America. For SEPA payments, consider opening an account in Portugal. For MENA trade, you will probably need a local financial solution in the UAE plus some minor foreign currency-denominated holdings (e.g., USD) that you can manage remotely using a local banking institution in Belize (e.g., for remote foreign currency dedicated deposits). Consider opening low foreign currency dedicated deposit accounts at remote regional Belizean banks.
7. Cayman Islands
Best for: Investment funds, captive insurers, family offices, and other corporations that are already utilizing the professional services available within the Islands’ financial centers of Grand Cayman and, to a lesser extent, Cayman Brac.
Why it made the list: The Cayman Islands offer a well-established and sophisticated financial center for funds, trusts, investments, and other business operations conducted within the jurisdiction. With 76 banks operating within the region of the Cayman Islands as at June 30, 2026 (CIMA), the majority of Category B licensed banks do not provide traditional retail banking services to non-residents.
Who should avoid it: People who are not residents of the Cayman Islands and require basic retail banking services such as money management services, current accounts, etc., with the ability to open accounts online from outside the island and have a local address link to the account(s) opened.
Non-resident account opening: Accounts can be opened by non-residents in limited circumstances where there is some connection to the Cayman Islands.
Remote opening: Cayman National has online banking with retail banking products, such as savings and current accounts, available for online application. Non-residents may be considered for account opening on a case-by-case basis.
Typical minimum deposit: Low for retail accounts held by residents in some banks. For offshore accounts held by private banking clients with large AUM, there may be higher minimum balances for various products and services offered by all international banks operating remotely within the Cayman Islands.
Typical ongoing balance: As indicated previously, this will vary depending upon the account(s) that the customer has within the bank to its customers.
Typical onboarding time: The average time for opening personal bank accounts and completing client files is around 4-12 weeks. Account opening for more complex entity accounts, such as trusts, etc., can take longer.
Fees: Bank fees include monthly account charges, administration charges, account opening fees, account closure fees, filing fees, and any other third-party fees. Trust and fund accounts have higher individual account fees than a standard retail account holder.
Corporate accounts: The corporate account is used most by funds and other companies set up in the Cayman Islands. Again, these must be properly administered and all operations transparently conducted.
Private banking: International banks with retail operations also offer private banking to their customers differently than in retail high street banks.
Currencies and international transfers: Cayman banks offer USD and KYD, while other currencies are offered by certain banks and through specialized services. Funds transfers via wire transfers are offered by most banks in the jurisdiction.
Privacy and reporting: This jurisdiction is subject to all international anti-money laundering/combating terrorism financing laws. It does not have direct income tax; however, all banking products for non-residents are introduced on an upfront basis, and all accounts are fully transparent. Clients must declare tax in other jurisdictions as applicable.
Main advantages:
- Well-established service provider with in-depth knowledge of funds, trusts, and other institutional structures.
- A well-established ecosystem supporting professional service needs;
- Strong alignment with structures based out of the Cayman Islands.
Main drawbacks:
- Many licensed banks do not accommodate ‘retail’ clients in a similar manner to that offered by traditional high street banks.
- While a local connection of the client is not necessarily a requirement to open bank accounts, some banks might need to verify such a link in their compliance procedures.
- Their cost even for the most basic accounts for individual customers is extreme.
Notable banks: Cayman National Bank and Butterfield Bank (Cayman), Butterfield Bank, RBC Royal Bank (Cayman), and others. For simple personal banking the alternative locations of Belize and Portugal might be more suitable.
Bottom line: Banks based in the Cayman Islands are able to effectively serve their clients with legitimate fund structures or investment vehicles established in the Cayman Islands. However, individuals looking for basic personal banking are better off looking at options offered in countries such as Belize or Portugal.
8. The Bahamas
Best for: This jurisdiction is ideal for high-net-worth individuals, trusts, and family offices from all over the world requiring a sophisticated foreign-currency private banking relationship in a tried-and-tested Caribbean financial services center.
Why it made the list: The Bahamas draws foreign-currency private banking business because of its sophisticated bankers and trusts, servicing an affluent client base. Foreigners can access specialized expertise and cross-border banking services of a top-tier Caribbean financial center.
Who should avoid it: Small transactional businesses, low-cost banking services in search of low-cost banking services, and people mistakenly believing that zero tax in the local currency automatically qualifies them for reporting exemptions in their home country should consider other alternatives.
Non-resident account opening: Yes. Non-resident clients can open accounts at a number of international as well as local banks with whom we can recommend good banking services. However, current KYC policies require full identification of new account openers and full validation of the source of wealth and the funds brought for banking.
Remote opening: Available via selected international banks and private banks and their network of intermediaries.
Typical minimum deposit: Moderate amounts. Foreign currency accounts are opened by private banks with moderate to high amounts of six figures and more plus corresponding investable funds.
Typical ongoing balance: Minimum amounts to keep in accounts to receive certain services under a private banking agreement, which can vary between banks and even between locations of the same bank.
Typical onboarding time: Approximately 4-12 weeks.
Fees: These can be varied depending on your banking relationship and will include account management, safekeeping of assets, cross-border payments, and other items and must be checked in advance with the bank, as these can vary very greatly.
Personal accounts: The customer can open Bahamian dollar accounts and hold foreign currency/international banking to link with local Bahamian accounts that the customer holds.
Corporate accounts: Corporate accounts can be opened. The purpose of and transaction history of the company will be evaluated on a case-by-case basis by the bank.
Private banking: Banking services offered to clients in need of customized financial solutions and of high value.
Currencies and international transfers: Foreign currencies such as the British pound and US dollar (particularly those that are actively traded on the international market) are often handled by the foreign currency banking arms of major banks. Specialized foreign currency banks also service their client base. Bahamian dollar-denominated accounts are subject to different exchange control rules than foreign currency accounts and are often classified as different account types.
Privacy and reporting: Account privacy in the Bahamas is protected by Common Reporting Standard (CRS) and Foreign Account Tax Compliance Act (FATCA) regulations administered by the Central Bank of the Bahamas and differentiating between local and non-resident account holders.
Main advantages:
- Experienced private wealth management and trust sector
- Options for foreign-currency international banking
- An English-speaking legal environment
Main drawbacks:
- Potentially high minimum asset requirements;
- Please note that account types and foreign currency-denominated accounts are subject to certain classifications under the bank’s exchange control policy and eligible products.
Notable banks: Butterfield Bank (Bahamas), Bank of The Bahamas, Deltec Bank & Trust, and Capital Union Bank, subject to current client acceptance.
Bottom line: The Bahamas is suitable for individuals looking for private wealth and/or trust linked banking structures provided minimum relationship thresholds can be met. For a lower entry point into foreign currency-denominated bank accounts, consider Belize, and for an institutional structure, consider the Cayman Islands.
9. Belize
Best for: Belize’s simple banking system is suited for foreign-currency savings or transactional accounts held by international clients with relatively small amounts of funds to deposit and manage at banks located in this country. Foreign-exchange-denominated savings and/or transactional accounts held by overseas customers with relatively small amounts of funds are well managed at banks located in Belize.
Why it made the list: Belize makes the list for a number of reasons, including the country’s specialist knowledge of international banking and the ease with which a foreigner of any nationality can open up an international bank account in Belize provided he can verify his nationality and prove his current address as a resident worldwide. Currently the minimum opening balance for select demand-deposit accounts and savings accounts at Caye International Bank is $30,000. However, previously there were accounts that could be opened with less than $2,000.
Who should avoid it: Larger corporations may find the banking in Belize is insufficient to handle their needs, as a larger financial center could offer. For example, a larger company would require more than one correspondent bank and may also require very complex treasury functions that a single bank in Belize could not provide.
Non-resident account opening: Yes, foreign nationals of any country and even resident foreigners can open an international account with banks in Belize as long as they provide proof of nationality and current residential address as required by law and by account-opening policies and procedures.
Remote opening: Yes, by certifying copies of identity documents such as a driver’s license along with current address proof such as utility bills. Also, it requires bank references and proof of the source of funds to open accounts in Belize and identify account holders under anti-money laundering rules.
Typical minimum deposit: Published Caye Bank products require a minimum opening balance of US$3,000 (or equivalent) for foreign currency cash accounts and a minimum opening balance of US$2,500 (or equivalent) for foreign currency savings accounts. There are a number of other foreign currency accounts as well as accounts in local currency that have different minimum opening balances.
Typical ongoing balance: This will depend on the account selected by you and we can advise of any ‘fall-below’ charges as well as inactivity charges and the relevant account balance(s) required to avoid such charges.
Typical onboarding time: Approximately 2-8 weeks.
Fees: The various account-related fees (maintenance fees for accounts, incoming and outgoing wire transfer fees to and from abroad for accounts in different currencies,, etc.) charged by correspondent banks as well as intermediary fees.
Personal accounts: In Belize, international banks operating from the country offer a full range of personal banking accounts and products.
Corporate accounts: Most international banks have a branch in Belize and can open up a corporate account for their clients upon provision of incorporation documents and Beneficial Owner Information for Know Your Customer compliance purposes and details of proposed business activities, of expected transactions etc.
Private banking: Not available in Belize to the same extent and quality as would be found in financial centers like Switzerland, Liechtenstein, Singapore, or the Bahamas.
Currencies and international transfers: USD currency and account options are available with some of the banks, and they are slowly introducing other foreign currencies. Transfer times for international wire transfers may vary from bank to bank via their correspondent banking networks.
Privacy and reporting: Information with respect to customers will not be treated as confidential by Belize and shall be disclosed in accordance with the requirements of CRS/FATCA as well as with any other legislation and/or lawful request from any government authority and/or regulatory body.
Main advantages:
- Lower entry threshold relative to major private-banking centers;
- Remote-oriented onboarding options available at select institutions;
- Documentation provided in English alongside foreign-currency offerings.
Main drawbacks:
- Limited number of international banking institutions present;
- Changes among correspondent banks may impact payment routes;
- Certain counterparties might impose additional compliance checks.
Notable banks: Caye International Bank and other institutions currently licensed by the Central Bank of Belize. Belize Bank and Atlantic Bank primarily serve different/local market segments and should not automatically be described as offshore-account options.
Bottom line: Belize thus offers an attractive solution for opening foreign currency accounts online with lower minimum account balances than would be offered by other major private banking centers worldwide (such as Switzerland and Singapore for investments, or even Portugal for SEPA transactions).
10. Nevis
Best for: Individual(s)/company(ies) owner(s) of Nevis company(s), international entrepreneur(s) with established business plan(s), and established banking relationship to expand legitimate global assets of estate.
Why it made the list: We consider Nevis banking in relation to the very active corporate and trust sector for Nevis LLCs and Nevis Trusts. This topic is covered in some detail, as there are several banks in Nevis that can service remote personal and corporate account applications.
Who should avoid it: This jurisdiction is not suitable for people looking for a broad range of banking services or immediate opening of a bank account to manage an estate when forming an LLC associated with a Nevis company or trust. Also, a local bank branch with a counter for informal transactions at a small account would not be an option for this jurisdiction.
Non-resident account opening: Non-resident accounts can be opened at individual banks, usually on a selective basis, and considered separately from the account holder’s company/trust, etc., registered with the company registry or trust company.
Remote opening: Some banks in Nevis consider opening remote accounts for natural or legal persons. The applicant needs to provide notarized/certified copies of completed and signed KYC questionnaires together with other required documents. Video verification of the applicant may also be required. Account opening is subject to discretion of the bank, and even if the company has been registered online through the Nevis company registry’s website, the bank may not open an account.
Typical minimum deposit: Minimum Account Size for Specialist International / Private Banking Products: $50,000 / $100,000 and above (depending on bank and the type of account product on offer). Minimums for local accounts will typically vary from these amounts.
Typical ongoing balance: Varies by bank.
Typical onboarding time: 3-10 weeks, depending on the amount of complete documentation supplied by the client. Additional time to complete applications of a more complex nature (e.g., larger corporate entities or a high-risk country of origin of the applicant(s)).
Fees: As mentioned above, fees may vary between different accounts and even different products offered by a bank. These may include account opening, analysis of client for compliance purposes, account administration on a monthly basis, and fees for processing of wire transfers, to mention a few. Even introducers may charge a fee in some instances.
Personal accounts: Available selectively.
Corporate accounts: These are the standard bank accounts that St. Kitts & Nevis companies can apply for. To open a corporate account, a company must be able to supply sufficient proof of the lawful nature of its business activities and its intended use of the account. Typically, this would involve providing details of its counterparties, contracts, and sources of funds for its business activities.
Private banking: Offered by a few banks, often in the form of specialized banking products, which require a minimum amount to open an account and maintain it.
Currencies and international transfers: All major currencies and all other currencies where a bank maintains a correspondent banking relationship.
Privacy and reporting: While St. Kitts & Nevis is one of over 90 jurisdictions participating in the Common Reporting Standard (CRS) initiatives as well as FATCA (USA) and other similar legislative bodies worldwide, banking confidentiality does not equate with anonymity. All cash held in bank accounts is subject to tracking. However, this does not mean that effective asset protection strategies cannot be implemented through the use of a properly structured Nevis LLC or trust.
Main advantages:
- Potential alignment with a Nevis company or trust;
- Remote applications accepted at selected banks;
- English-language corporate and banking documentation available.
Main drawbacks:
- Limited number of banks operating within this market;
- Entity formation does not guarantee account approval at any given bank.
- If a bank has correspondent relationships for wire transfer of currencies, then list out the currencies and minimum balance requirements for accounts for each currency.
Notable banks: Some banks that operate accounts in Nevis are The Bank of Nevis Limited and other international bank institutions.
Bottom line: In summary, establishing a banking relationship in Nevis will likely be more suitable for clients who have prior connections to a structure in Nevis and who can successfully secure approval for a banking arrangement with a suitable bank. For those seeking to establish lower balance accounts, either as individuals or as a standalone company, Belize may offer greater options, while the Bahamas offers more comprehensive private wealth management solutions.
Best Offshore Banking Country by Client Profile
Even though some countries may offer a more developed system of offshore banking, it does not mean that one country is better than others for all clients. Our team of experts has extensive knowledge of offshore banking in various countries, and we will recommend a jurisdiction based on the client’s residency, occupation, amount of capital to be deposited into an offshore bank account, and the purpose for which the offshore bank account is to be opened.
Best for HNW Individuals
For high-net-worth individuals (HNWI), we compare four top locations for wealth investments worldwide: Switzerland, Liechtenstein, Singapore, and the Bahamas.
For cross-border wealth management, the client looks to Switzerland for top private banking services. The services of a Liechtenstein family foundation are additionally considered by families with the goal of wealth management across generations. Families from Asia choose Singapore as the preferred location for their asset management as many HNW individuals are also businesspeople and/or have investments on the Asian continent. The financial center of the Bahamas is an ideal location for setting up trusts. The location also offers a complete portfolio of additional services that are needed for optimal private wealth management.
When comparing these locations, aspects such as clients’ requirements for portfolios that can be easily moved across borders, their preference for direct or indirect contact with their wealth manager, and the number of transactions between different locations are considered.
Best for International Business
A business account is most beneficial for a company that establishes the account itself and then uses it in its own operations. Thus, a small local business with employees and customers in the UAE will derive more benefits from opening a business account in the UAE than a trading company already well established and operating throughout Asia that opens a business account in Singapore.
Opening a Panama business account can be especially useful for people who frequently send U.S. dollar payments to customers or suppliers in Latin America. Also, opening a euro-denominated business account in Portugal (part of SEPA) will give significant added value for people conducting frequent euro transactions with customers or suppliers in Europe.
Best for Low Minimum Deposits
Opening an offshore bank account does not require a large amount of money to be deposited to open the account. Many banks and financial institutions have minimum deposit requirements for new individual and company accounts, but there are now a number of offshore banks that offer a range of personal and business bank accounts with lower minimum deposits to open.
For example, Caye International Bank in Belize requires a minimum deposit of US$3,000 for some products and client types. We advise you to verify this requirement with the bank for specific products and account types and also for the the minimum balance required to maintain the account(s).
Best for Remote Opening
As non-citizen individuals of Belize and Nevis, respectively, there are several ways that individuals can open up offshore accounts online through intermediaries to establish offshore online accounts for their entities. They can even set up a digital business account in Portugal to run their offshore business entity in the EU in their offshore account holder name.
Note: Eligibility criteria to open an online account for non-resident individuals vary from bank to bank in the UAE. While some banks offer a 100% online account opening process to non-residents, others would require a physical meeting with a bank representative and a branch visit in countries such as Switzerland, Liechtenstein, Panama, the Cayman Islands or Bahamas. We have a network of licensed intermediaries worldwide who can open online accounts for our clients in different countries including online business accounts in Portugal that can be used to receive money and pay out within the EU — often referred to as offshore accounts.
Best for EU and SEPA Access
Establish and maintain customer relationships and supply relationships in European countries in which you conduct business and open a euro account in Portugal to make use of SEPA payments.
A market-oriented view of Europe for our clients from Liechtenstein provides a lot of opportunities: not only personal asset management for long-term family assets, but also corporate services offered by many private banks. The offer of services by trust companies is equally broad and is offered by many private banks. As with commercial banks within the EU, the minimum requirements and the business conditions of private banks can differ significantly from one another. It is therefore important to know what to expect.
Key Country Comparisons
Which banking destination is best for you? A comparison of account requirements, residency conditions, and acceptance rates of banks from the countries presented here.
Switzerland vs Liechtenstein
Switzerland generally offers a greater variety of banks and a broader range of financial services than is available in Liechtenstein. For services relating to foundations, trusts, and succession, however, there is a much greater choice of banks in Switzerland, offering a more comprehensive service. Both countries have minimum account sizes and require international reporting for their account holders.
UAE vs Singapore
Banks in the UAE with account services in local languages and business ideas to enhance cash flow and trade within the MENA region are of interest to residents. On the other hand, individuals from Asia with significant investable assets may look at opening a bank account in Singapore to explore more opportunities.
Belize vs Nevis
Banking in Belize offers up international savings accounts and payment accounts with very low minimums to keep. A savings account in Nevis can be opened but typically needs to be done through a recognized entity or trust that has been validated by the bank as qualified to open said account(s). The assets in said account(s) will be protected, but NOT the account nor the assets in the account if held in the name of anonymous owners or entities.
Risks and Limitations of Offshore Banking
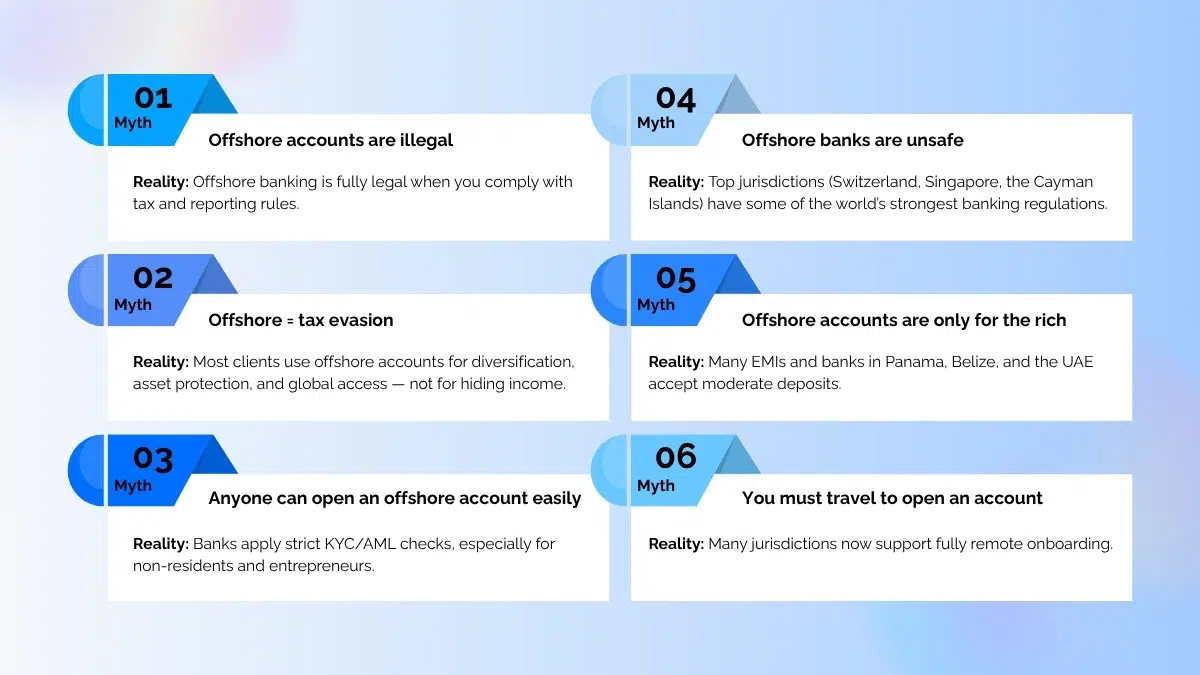
Account opening is at the complete discretion of the bank in question. We have listed below the most common reasons for account applications being rejected.
- The applicant is a citizen or resident of a country that is classified as high-risk or a sanctioned jurisdiction, and/or the account will be used for transactions into such a country.
- The bank’s risk policy does not cover the specific industry of the applicant.
- There is unclear ownership or an unaccounted-for nominee.
- Insufficient evidence provided to verify the origin of funds/deposits.
- Insufficient expected average functional balance to cover the bank’s compliance expenses.
- Offshore companies lacking adequate ‘substance’ to establish a credible business presence in a foreign jurisdiction may encounter problems when applying for an offshore bank account. Typically this type of company will have little or no credible business history and, as an example, will have no website, no contracts, no invoices, etc.
- The pattern of payments deviates from the initially approved account profile.
- The bank has evidence of tax evasion, or the provided tax documents do not match the information given by the applicant.
The bank continuously monitors transactions that are performed via the bank’s accounts. In individual cases, monitored transactions may be subject to further requirements for documentation and information (e.g., a copy of the prior year’s tax return, contracts, invoices, etc.). A monitored transaction may be postponed or even rejected and (where relevant) refunds made via intermediary banks. In monitored transactions that exceed the parameters of the approved account profile for the account holder, accounts may be subject to restrictions or even closed.
This information can be found on our website by clicking here to view the most up-to-date list of countries that are considered to be of higher risk or under greater scrutiny by the FATF and how their country of domicile may affect account opening at different banks.
How Much Does Offshore Banking Cost?
| Cost | Typical range or treatment |
| Bank application/opening fee | Often zero to several thousand euros/dollars; specialist or intermediary-led cases cost more |
| Minimum opening deposit | About EUR 250 at accessible EU retail level to CHF/US$500,000-5 million+ for wealth tiers |
| Monthly/annual account fee | Roughly EUR/US$5-100+ per month for ordinary/specialist accounts; private-bank pricing is often asset-based |
| International transfer | Flat bank fee plus correspondent and FX charges |
| Custody/advisory/management | Percentage of assets or transaction-based; request the total expense ratio |
| Certification/apostille/translation | Depends on document count and country |
| Company, trust or foundation | Separate formation, registered-agent, accounting, audit and annual-government costs |
| Compliance refresh | Some banks charge review or non-compliance fees; late KYC can lead to restriction |
Annual cost model should reflect all costs (not just the opening fee) and be calculated based on expected balance * volume of transactions + FX spread on incoming wires + FX spread on outgoing wires + FX spread on card transactions + banks’ custody fees and maintenance charges and charges from other service providers, etc.
How to Open an Offshore Bank Account
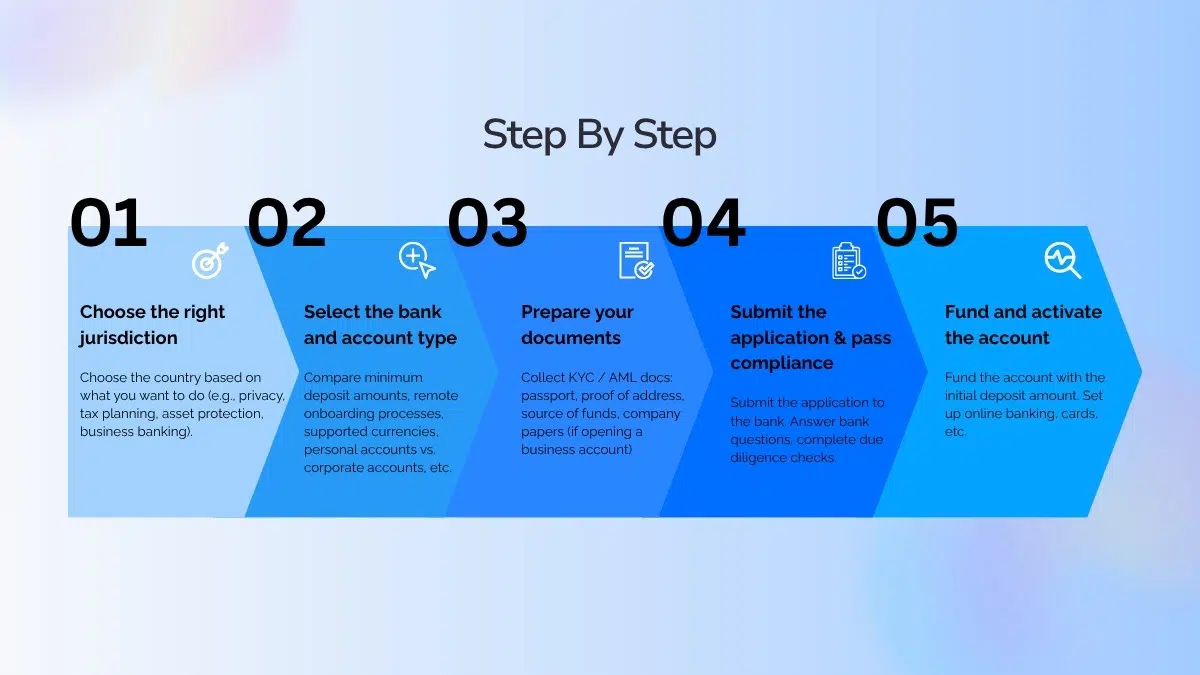
Opening an offshore bank account usually requires a bit more paperwork than opening an account with a local bank. The account application form for offshore bank accounts typically requires a lot of information and includes questions about the reason for opening said account, the origin of deposits, and future transactions.
- Information on the reason for opening an offshore bank account, the origin of deposits, and the nature of proposed transactions will be required. This information will be used to clarify your objectives for requiring an offshore bank account (e.g., saving, investing, conducting international payments, or distribution of funds from a trust or persons now resident abroad).
- When comparing the range of products offered by banks to their respective client base, it is also important to look at the accepted nationalities and countries of residence of customers as well as the available currencies to open an account. Account opening online, minimum account balances, as well as periodic maintenance fees and charges for outgoing wire transfers, are further considerations. Banks also vary with the range of additional services offered for the payment of checks and other bills.
- Information required is proof of the customer’s current place of residence. Customer identification documents, tax returns, confirmation of the customer’s employment or confirmation of a company and principal executives, directors, and shareholders of the company, and furthermore, confirmation of principal executives, directors, shareholders, and beneficiaries of said shareholders may be required.
- Most banks will require you to provide a full explanation as to the source of any funds deposited into your account and the intended use of said funds. Once you have opened your offshore bank account, you can deposit and withdraw funds as you see fit. The offshore bank account would function in exactly the same manner as a normal bank account, which you would open at a standard banking institution within your own country.
- Compliance check: There is a quick compliance check through an on-line form to determine if an offshore banking account would be suitable for you. Once approved, an account is opened, and you need to fund the account within a certain time frame. From then on all correspondence with the bank needs to reflect any changes in the client’s profile or in the intended activity of the account.
Opening an offshore bank account will usually require the assistance of a banking specialist who can go look for the right bank for you, complete any pre-screening on your behalf, and assist with the preparation of the application. However, remember approval of any bank account application is always at the complete discretion of a bank’s compliance department and therefore can never be guaranteed.
Documents You Will Usually Need
Below are several essential documents that an individual may need to provide:
- A scanned copy of the applicant’s valid passport(s) plus any additional country-specific identification required by financial institutions.
- Recent proof of residential address;
- Tax identification number and CRS/FATCA self-certification;
- Curriculum vitae or professional profile;
- Bank reference or recent bank statements;
- This may include proof of current salary, recent dividends, sales proceeds from a property, etc. along with relevant supporting documentation to facilitate the funding of accounts that have been opened.
For a company or entity, banks typically request:
- Register of directors, shareholders, and beneficial owners;
- Certificate of good standing for established companies;
- An organizational chart of the company that clearly outlines the reporting structure. A written description of the ownership structure.
- Business plan, website information, contracts, invoices, and licenses;
- Details about the expected counterparties (countries & currencies) as well as the average monthly business volume expected to be conducted with these parties.
- Board resolution and authorized signatory documentation;
- Trust deed or foundation documents plus details about any protectors and/or trustees and their respective roles.
- Board resolution and authorized signatory documentation;
- Trust deed or foundation documents plus details about any protectors and/or trustees and their respective roles.
Conclusion
To choose the most suitable offshore banking location for a client’s specific needs, one must have a clear and accurate understanding of the client’s complete and true profile and not simply choose one of the more popular locations, such as Switzerland, Liechtenstein, or Singapore, with its huge pool of investment wealth. For example, individuals living in the UAE may find that establishing a personal offshore bank account with a quality Portuguese bank (based within the EU/SEPA area) is the most suitable option as their primary offshore banking facility.
Responsible business people from Latin America hold their USD cash offshore from Panama, for example. Others are served by the treasury department of the Cayman Islands or enjoy the world-class banking facilities of the Bahamas. Offshore bank accounts in well-secured branches of banks in Belize are available to clients who have set up an appropriate offshore structure within a comprehensive Nevis structure. Offshore Pro Group can review a list of prospective offshore banks on behalf of our clients and assist with completing account applications; however, the decision to open an account is made solely by the offshore bank.
Frequently Asked Questions
Is it legal to have an offshore bank account?
Generally, an offshore bank account can be opened. There are several factors to consider in establishing and maintaining an offshore account. These factors may include the source of funds, account use, and even trade sanctions between countries. In addition, a bank will ask for identification of the beneficial owner and information concerning his tax residence.
Are offshore accounts anonymous?
Offshore accounts are typically held in confidence by banks. Account holder identities and transactions conducted via accounts held abroad are generally not disclosed to third parties. Account holder identification, beneficial owner(s) identification, and tax residence details will be required by most jurisdictions in order to establish an offshore account. Reporting requirements are also in place for many jurisdictions under the Common Reporting Standard (CRS) and/or Foreign Account Tax Compliance Act (FATCA), for example. The tax authorities of the account holder’s tax residence will receive the required information regarding the account holder(s).
Can a US citizen open an offshore account?
U.S. citizens can typically open foreign bank accounts at foreign banks and at branches of foreign banks abroad. In some instances, U.S. persons holding offshore accounts may be required to file additional U.S. tax returns (e.g. FATCA Form 8938 (Report of Specified Foreign Financial Assets)) depending on the circumstances of the offshore account(s) held by such individual(s). As a result of FATCA, some foreign banks refuse to open accounts for U.S. persons due to the extensive reporting that such persons would trigger for the bank.
Can a UK resident open an offshore account?
Generally speaking, yes, individual banks have different policies and procedures in respect of new accounts. However, regardless of where in the world an offshore account is opened, the account holder will remain liable for all UK tax and will need to declare all foreign income and capital gains wherever these are received.
What is the safest country for offshore banking?
It’s a big question, and the safest country will depend upon a range of factors. As a general rule, wealthier countries such as Switzerland, Liechtenstein, and Singapore are most often associated with stability and high-end private banking services. Factors such as the safety of a bank itself (is it reputable? Is the account guaranteed?) and the issue of capital and currency (could there be limitations, for example, regarding foreign currency accounts?), as well as specific banking products and their structure, can all significantly affect the overall security of an offshore banking arrangement. Finally, good account management, clear and effective reporting, and above all sound diversification and proper investment planning all play their part.
What is the easiest offshore account to open remotely?
Belize is one of the more easily remote open offshore accounts. Then there are the various Caribbean banks, for example, banking in Belize. You can also apply remotely for banking services in Portugal by setting up a residency via Citizenship by Investment of a small business. Remember, however, that any application of this nature can change overnight, and so claims of guaranteed approval must always be viewed with caution.
Why can an application be rejected?
Unapproved applications can be for a variety of reasons. These might include lack of supportable wealth; association with high-risk countries; lack of transparency or unreasonable complexity in establishing the beneficial owners of accounts; discrepancies within submitted documentation; unsubstantiated or unduly aggressive cash flow projections; or low account balances in relation to required minimums for accounts of that type. Inability to establish a legitimate connection to the location of required banking facilities will also serve to decline any application.
Does an offshore account protect assets from creditors?
An offshore account itself is not going to be enough to protect your assets from creditors and must be combined with other, more advanced structures such as corporations, trusts, etc., set up in line with their specific laws to be effective in the given circumstances and jurisdictions.
How long does opening take?
An offshore bank account for an individual can take 2–8 weeks to open if straightforward, i.e., a normal online application and within the bank’s normal ‘offer’ criteria. This timescale will increase for a more complex account application, i.e., for private banking or of a higher risk nature, and this would be processed in 1–3 months or more.